PV.market Weekly Solar Market and Ready Stock Intelligence | 30 October 2026
Market coverage 23 to 30 October 2026 | Stock snapshot 26 October 2026
This week combines stronger project demand with uneven logistics and selective ready stock. The first section explains what changed across India, the Middle East, Africa and Europe. The second turns those signals into procurement choices using PV.market inventory dated 26 October and independent price and freight benchmarks dated 28-29 October.
Executive view
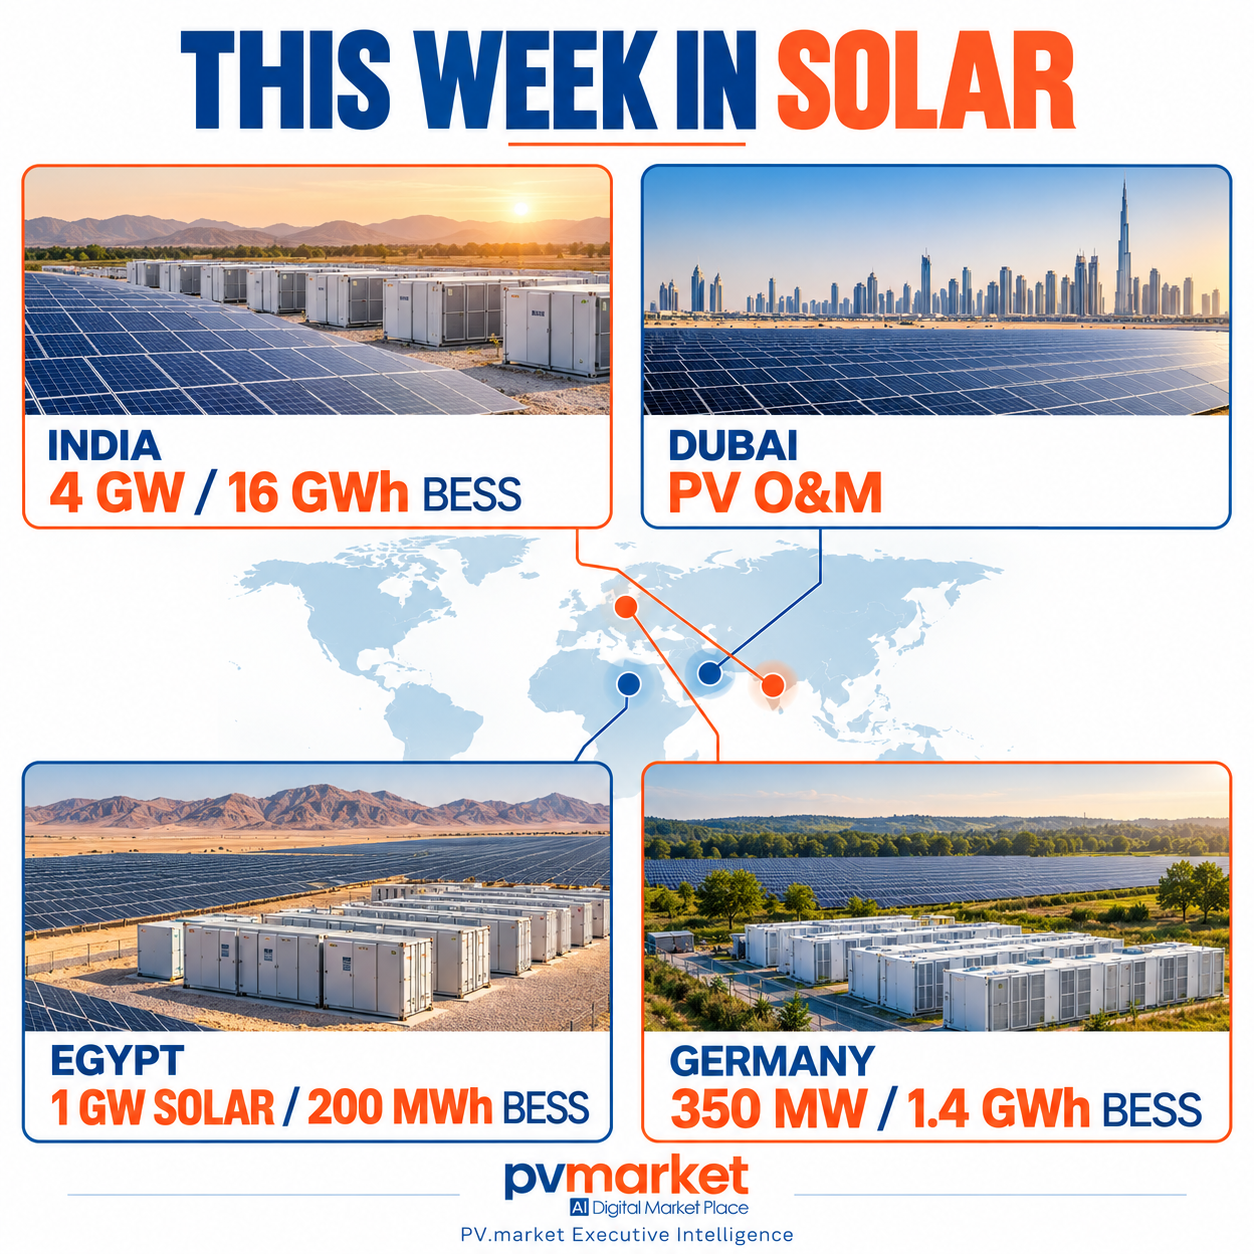
- India produced the largest new procurement signal: SECI published a 4,000 MW and 16,000 MWh standalone battery tender for Rajasthan and Gujarat on 28 October.
- Egypt advanced a USD 650 million, 1 GW solar and 200 MWh storage project toward financing, strengthening the African solar-plus-storage pipeline.
- Germany moved a 350 MW and 1,400 MWh battery project to financial close with EUR 260 million of debt financing.
- Module prices were broadly stable, while storage-cell and lithium prices softened. Complete ESS benchmarks did not yet decline.
- PV.market shows 412 qualifying listings from 60 brands across 15 warehouse locations. Regional stock can outperform factory-region supply when delivery time, freight and project risk are included.
Weekly solar market briefing
The regional briefing below covers confirmed, material developments published or updated during 23-30 October 2026. The commercial implications are PV.market interpretations and should be validated with each buyer, developer or tender authority before being treated as an RFQ.
India
- Confirmed development: SECI published a tender on 28 October for 4,000 MW and 16,000 MWh of standalone BESS in Rajasthan and Gujarat. Bids close 19 November. BHEL also published a corrigendum on 24 October for a 600 MW solar project with 275 MW and 550 MWh of BESS, with submissions due 31 October.
- Practical implication for PVmarket: Create two deal rooms immediately. Prioritise Indian BESS developers, EPCs, PCS and EMS providers, transformer suppliers, ALMM-compliant module manufacturers and partners able to provide bank guarantees and long-term service.
Middle East
- Confirmed development: Etihad ESCO opened an EOI on 23 October for rectification works and an online monitoring system at Wasl Properties Phase 1 Solar PV Project in Dubai. No new utility-scale open solar tender or major distribution-policy change was verified during the week.
- Practical implication for PVmarket: Use Dubai as an O&M and digital-monitoring opportunity rather than a primary-equipment sale. Onboard service providers with Shams Dubai experience, fault diagnosis, monitoring integration and local response capability.
Africa
- Confirmed development: Egypt announced a preliminary financing agreement on 26 October for Scatec's USD 650 million Dandara project: 1 GW of solar and 200 MWh of storage in two phases, with EIB, EBRD and AfDB participation.
- Practical implication for PVmarket: Map Scatec's EPC and procurement ecosystem before package awards. Focus on bankable modules, utility inverters, BESS, transformers, cables, spares and supply-chain documentation rather than generic distributor outreach.
Europe
- Confirmed development: GIGA Storage announced financial close on 26 October for the 350 MW and 1,400 MWh Albatross BESS in Germany, backed by EUR 260 million of debt. CATL will provide engineering, construction and maintenance, with European subcontractors.
- Practical implication for PVmarket: Germany remains the strongest bankable utility-storage target. The most realistic entry points are European subcontractors, transformers, fire protection, grid connection, auxiliary systems, spares and service rather than the core battery package.
Weekly pricing inventory and logistics signal
Modules. InfoLink's 28 October assessment placed the China TOPCon module average at RMB 0.717/W, down 0.3%, while the non-China average remained USD 0.114/W. TrendForce kept the 182 mm TOPCon module average at RMB 0.70/W. Finished-module prices therefore remained broadly stable despite mixed cell movements.
Storage. Battery-grade lithium carbonate fell 4.9% to RMB 97,000 per tonne, while 280 Ah and 314 Ah storage cells declined 0.7% to RMB 0.355/Wh. Complete two-hour and four-hour ESS benchmarks were unchanged at RMB 0.49/Wh DC-side, RMB 0.58/Wh AC-side for two hours and RMB 0.53/Wh AC-side for four hours.
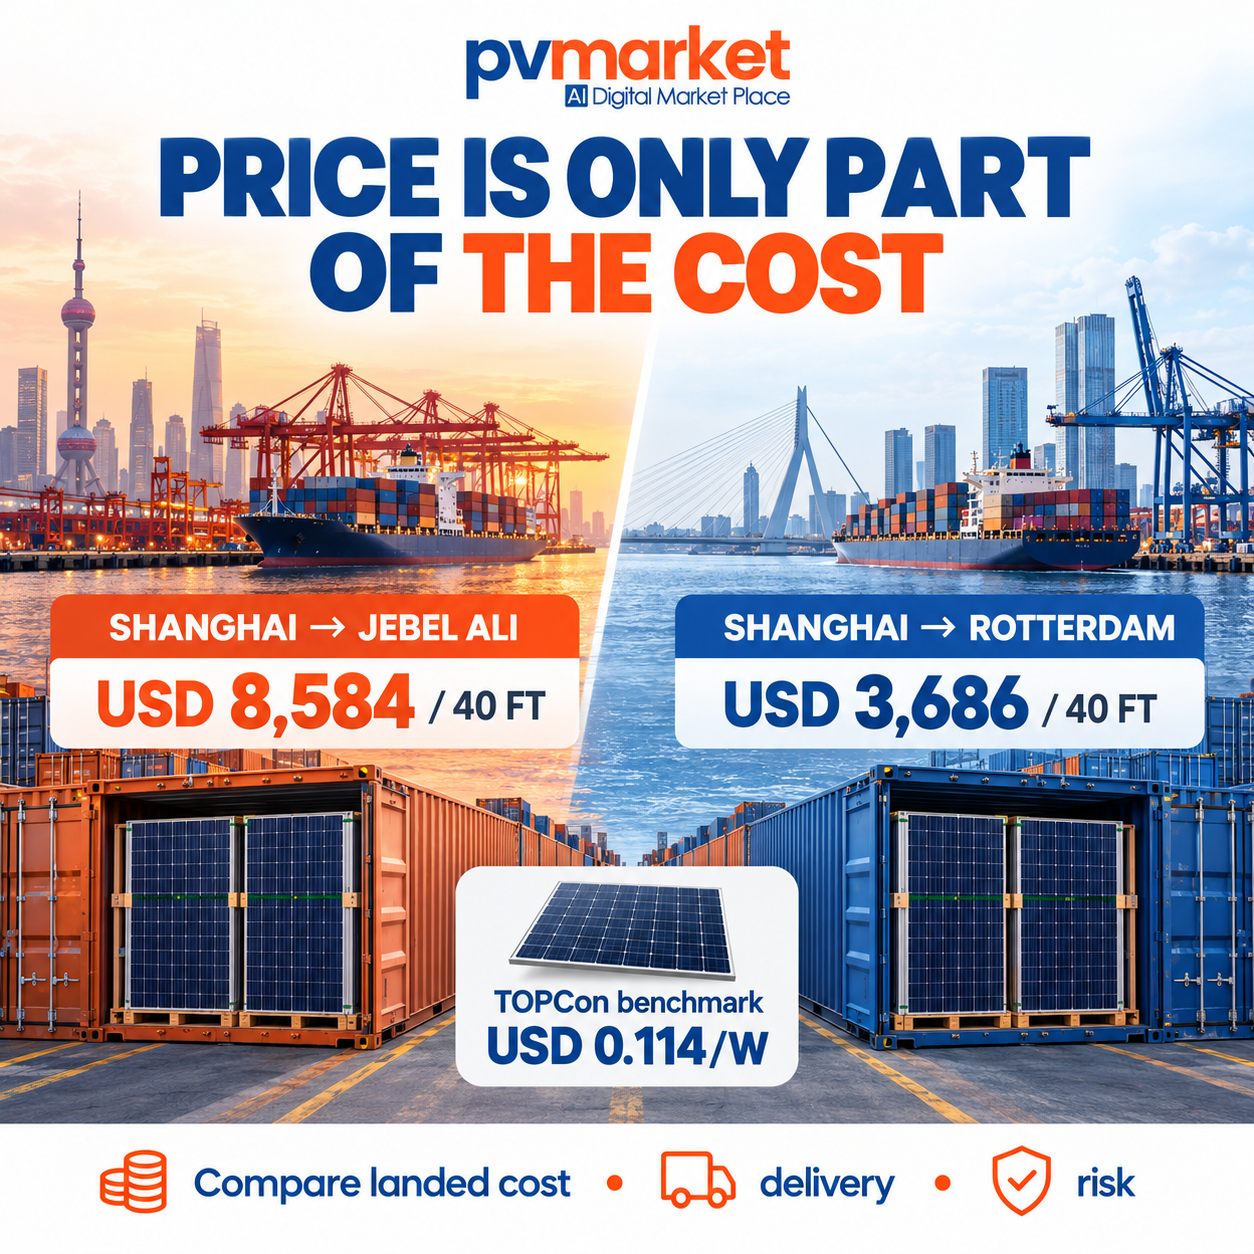
Logistics. Drewry's 29 October assessment put Shanghai-Rotterdam at USD 3,686 per 40-foot container and Shanghai-Genoa at USD 4,151. Shanghai-Jebel Ali remained much higher at USD 8,584 as Middle East disruption persisted.
PV.market inference. Buyer negotiating power remains strong for modules, but waiting for a broad price decline is unlikely to improve near-term project economics. For the Gulf, ready stock should be compared against freight-adjusted import cost and schedule risk. For Europe, lower freight keeps factory-region and local-stock competition tighter.
Marketplace and competitor activity
Confirmed. No material acquisition, funding round or major direct-marketplace launch was verified this week. Sun.store published its September Battery Index on 23 October: European low-voltage residential systems averaged EUR 94.4/kWh, high-voltage performance systems EUR 154.1/kWh, high-voltage premium systems EUR 315.3/kWh, and 60-120 kWh commercial systems EUR 199.2/kWh. Prices exclude VAT and delivery.
PV.market implication. The market is moving toward transaction-based price intelligence. PV.market should publish a weekly, clearly scoped ready-stock index with warehouse, quantity, technology, Incoterm and data date so buyers can understand why two apparently similar products have different prices.
No meaningful change this week
- No consequential public inverter-price movement was verified.
- No new regional solar trade measure or distribution regulation requiring an immediate strategy change was verified.
- No direct solar B2B marketplace acquisition, funding round or major platform launch was verified.
Regional commercial comparison
India
- Current demand signal: Strongest immediate BESS and solar-plus-storage RFQ pipeline
- PVmarket execution priority: Deal-room execution and compliance-led seller onboarding
Middle East
- Current demand signal: Limited new utility procurement; active O&M and monitoring demand
- PVmarket execution priority: Monetise ready stock and local service capability
Africa
- Current demand signal: Large financed projects concentrated in Egypt
- PVmarket execution priority: Project-specific developer and EPC mapping
Europe
- Current demand signal: Bankable utility storage and selective C&I demand
- PVmarket execution priority: Buyer-led growth with strict bankability and origin data
PVmarket solar procurement and ready stock intelligence
The market briefing explains where demand is forming. The following stock analysis shows what PV.market can offer now and where ready inventory carries a commercially justified premium.
PVmarket stock coverage
The 26 October inventory file reviewed 419 source rows and retained 412 after applying the stated module-quantity filter. The regional distribution below shows where PV.market can support immediate RFQs and where stock depth is limited.
United Arab Emirates
- Listings: 158
- Commercial reading: Deepest ready-stock mix, especially inverters, hybrid systems and BOS
China
- Listings: 82
- Commercial reading: Largest choice of competitively priced modules and storage systems
Europe
- Listings: 57
- Commercial reading: Strong module and inverter availability across seven warehouse countries
India
- Listings: 35
- Commercial reading: Local-currency modules and on-grid inverters; compliance must be checked
South Africa
- Listings: 29
- Commercial reading: Distributed module, inverter, battery and BOS availability
Nigeria
- Listings: 26
- Commercial reading: Local stock available, but modules show a material regional premium
Oman
- Listings: 21
- Commercial reading: Current file is concentrated in BOS and accessories
Jordan and Georgia
- Listings: 4
- Commercial reading: Limited specialist stock; use RFQ-led sourcing
PVmarket module price comparison
The comparison uses selected rigid modules of 580W or more and commercially relevant quantities. It excludes flexible and low-watt products. Prices remain in their listing currency so local markets are not distorted by an assumed exchange rate.
China
- Selected price range: USD 0.099-0.145/W
- Median: USD 0.116/W
- What it means: Lowest entry price and broadest utility-format choice; freight and lead time remain decisive
UAE
- Selected price range: USD 0.129-0.151/W
- Median: USD 0.142/W
- What it means: Ready-stock premium can be justified when project schedules cannot absorb import delays
Europe
- Selected price range: EUR 0.099-0.113/W
- Median: EUR 0.104/W
- What it means: Competitive regional stock with lower inbound freight than Gulf routes
South Africa
- Selected price range: USD 0.139-0.153/W
- Median: USD 0.147/W
- What it means: Local availability reduces import and delivery risk for installers and distributors
Nigeria
- Selected price range: USD 0.168-0.180/W
- Median: USD 0.177/W
- What it means: Higher local-stock premium supports container consolidation and forward procurement
India
- Selected price range: INR 14.42-18.42/W
- Median: INR 16.15/W
- What it means: Keep domestic-content and non-DCR products in separate comparisons
Important India distinction. The file includes a 535W DCR example at approximately INR 28.69/W. It is a single listed offer with limited quantity, not a market average, but it demonstrates why DCR and non-DCR products should never be benchmarked together.
Benchmark context. PV.market's selected China median of USD 0.116/W is close to InfoLink's USD 0.114/W non-China TOPCon benchmark, while the lowest reviewed China offers are below USD 0.100/W. In Europe, the selected PV.market median of EUR 0.104/W is approximately 8.8% below sun.store's September TOPCon bifacial average of EUR 0.114/W. These comparisons are indicative because brand, power class, quantity, Incoterm, certification, delivery and payment terms differ.
Selected ready-stock examples
China — Q-Sun 620W
- Available quantity: 3,700
- Unit price: USD 61.65
- Normalised price: USD 0.0994/W
China — Solar N Plus 630W
- Available quantity: 15,000
- Unit price: USD 62.94
- Normalised price: USD 0.0999/W
China — Ronma 730W TOPCon
- Available quantity: 13,200
- Unit price: USD 73.69
- Normalised price: USD 0.1009/W
UAE — RECOM 620W TOPCon
- Available quantity: 6,480
- Unit price: USD 79.83
- Normalised price: USD 0.1288/W
UAE — Trina 730W TOPCon
- Available quantity: 2,970
- Unit price: USD 103.76
- Normalised price: USD 0.1421/W
Europe — Tongwei 635W N-Type
- Available quantity: 15,000
- Unit price: EUR 62.79
- Normalised price: EUR 0.0989/W
Europe — LONGi 620W Hi-MO 7
- Available quantity: 3,600
- Unit price: EUR 63.22
- Normalised price: EUR 0.1020/W
South Africa — Astronergy 625W TOPCon
- Available quantity: 576
- Unit price: USD 86.83
- Normalised price: USD 0.1389/W
Nigeria — LONGi 625W Hi-MO 7
- Available quantity: 720
- Unit price: USD 105.06
- Normalised price: USD 0.1681/W
India — Novasys 630W TOPCon
- Available quantity: 1,000
- Unit price: INR 9,084.60
- Normalised price: INR 14.42/W
How freight changes the Gulf comparison
PV.market inference. For a representative container carrying 720 modules, the current Shanghai-Jebel Ali rate alone adds roughly USD 0.016-0.019/W for 620-730W products, before terminal handling, insurance, customs and inland transport. A China listing near USD 0.100/W can therefore approach USD 0.116-0.119/W before other landed costs. The gap versus UAE stock narrows materially, and immediate availability may be commercially preferable when a delay risks project penalties or lost installation capacity.
Europe has a different freight signal. Shanghai-Rotterdam was USD 3,686 per 40-foot container and Shanghai-Genoa USD 4,151. For the same representative module range, ocean freight is approximately USD 0.007-0.009/W before destination charges. This supports a more price-driven procurement approach in Europe than in the Gulf, provided certification and delivery schedules are secure.
Inverter and battery price signals
Price normalisation is also useful beyond modules, but product specifications are less standardised. The examples below are directional and must be checked against topology, phase, voltage, certification, warranty, cycle life, depth of discharge, BMS compatibility and commissioning scope.
Residential battery China
- Selected offer: Genixgreen 16.08kWh at USD 1,300.05
- Normalised indication: USD 80.85/kWh
- Commercial interpretation: Low equipment price; confirm cells, certification, warranty and freight
Residential battery UAE
- Selected offer: Power & Sun Tusk WFR 5.12kWh at USD 508.20
- Normalised indication: USD 99.26/kWh
- Commercial interpretation: Ready stock reduces lead time; compare usable capacity and warranty
Residential battery Nigeria
- Selected offer: Deye 16kWh at USD 1,916.25
- Normalised indication: USD 119.77/kWh
- Commercial interpretation: Local support and import cost contribute to the regional premium
C&I ESS China
- Selected offer: Genixgreen 215kWh and 100kW at USD 37,600
- Normalised indication: USD 174.88/kWh
- Commercial interpretation: Includes power-rating scope; verify PCS, EMS, fire system and commissioning
Hybrid inverter China
- Selected offer: Genixgreen 16kW at USD 1,368.52
- Normalised indication: USD 85.53/kW
- Commercial interpretation: Volume-tier reference only; not directly comparable across topology
Hybrid inverter UAE
- Selected offer: Power & Sun 6kW at USD 464.68
- Normalised indication: USD 77.45/kW
- Commercial interpretation: Regional stock can be competitive when model suitability is confirmed
What buyers should compare before ordering
- Use price per watt, price per kilowatt or price per kilowatt-hour only after confirming that the technical scope is comparable.
- Request the warehouse location, available quantity, manufacturing date, datasheet, certification and serial-number or batch evidence.
- Compare EXW, FOB, CIF and delivered pricing separately. Do not mix a factory quotation with local ready stock.
- Include freight, insurance, customs, terminal charges, warehousing, inland delivery and financing cost in the landed-cost calculation.
- Confirm warranty route, local service capability, delivery date and quotation validity before issuing a purchase order.
What sellers should do
- Keep quantity, price tier, warehouse location and deliverable countries current.
- Provide model-level certificates and datasheets so buyers can compare like for like.
- Use Real-Time pricing when fixed prices cannot be maintained and respond quickly to verified RFQs.
- Show whether prices include or exclude freight, tax, insurance and marketplace service charges.
- Prepare container-level offers for Africa and Gulf markets, where logistics materially affect the final price.
Five priorities for the coming week
1. Open India project deal rooms. Map bidders and suppliers for SECI's 4,000 MW and 16,000 MWh BESS tender and BHEL's 600 MW solar plus 550 MWh storage package.
2. Map financed project procurement. Identify procurement decision-makers and subcontract packages around Egypt's Dandara project and Germany's Albatross BESS.
3. Publish a verified PVmarket stock index. Use five to ten reconfirmed products and show price per watt, kilowatt or kilowatt-hour together with warehouse, quantity, Incoterm and data date.
4. Reprice Gulf-bound offers. Compare China-origin supply with UAE ready stock using current freight, delivery risk, customs, insurance and inland transport rather than FOB price alone.
5. Strengthen RFQ and seller data. Add ALMM and DCR status, component origin, grid-forming capability, local certification, warranty route, delivery deadline and price validity to relevant listings and RFQs.
How to use PVmarket prices
PV.market is a neutral B2B marketplace. Buyers should treat newsletter prices as market intelligence and RFQ starting points, not binding offers. Stock, price and availability must be reconfirmed before a pro forma invoice is issued. Unless a quotation states otherwise, freight, tax, insurance, customs, warehousing and delivery may be additional. The standard marketplace service fee is 3% for modules and 5% for other product categories.
Buyer call to action. Send an RFQ with the product category, capacity, quantity, delivery country, preferred Incoterm and required delivery date. PV.market can compare available regional stock with factory-region supply while keeping sellers anonymous during sourcing.
Sources
- PV.market Weekly Stock Update 26 October 2026
- SECI Tenders 28 October 2026
- BHEL Solar and BESS EPC Tender Update 24 October 2026
- Etihad ESCO Ongoing Tenders 23 October 2026
- Reuters Egypt Dandara Project 26 October 2026
- GIGA Storage Albatross Financial Close 26 October 2026
- InfoLink Consulting PV Spot Price Update 28 October 2026
- InfoLink Consulting ESS Spot Price Update 28 October 2026
- Drewry World Container Index 29 October 2026
- Drewry Intra Asia Container Index 29 October 2026
- sun.store Battery Index September 2026 published 23 October 2026
PV.market Where online and offline distribution operate as one
Leave a Comment
Comments
No comments yet. Be the first to comment!